WW/OCEANFREIG
Icon Energy Buys 2.8% Stake in 1,800 TEU Feeder at $24,750 a Day
Icon Energy agreed to buy a 2.8% stake in an owner of a 1,800 TEU 2023-built feeder chartered at US$24,750 daily through February 2028, its second containership minority deal.
- Desk
- Ocean Freight
- By
- James Calloway
- Filed
- Length
- 571 words
- Read
- 3 min
Key points04
- Icon Energy agreed to acquire a 2.8% minority interest in a company owning a 1,800 TEU ECO containership built in 2023.
- The vessel is chartered at US$24,750 per day, with minimum employment through February 2028 and about US$12 million in minimum contracted charter revenue.
- Closing is expected by end-October 2026, subject to definitive documentation and customary conditions; the price was not disclosed.
- Icon Energy's earlier deal is a 4.6% stake in a 2008-built 2,000 TEU feeder earning US$26,500 per day through June 2028.
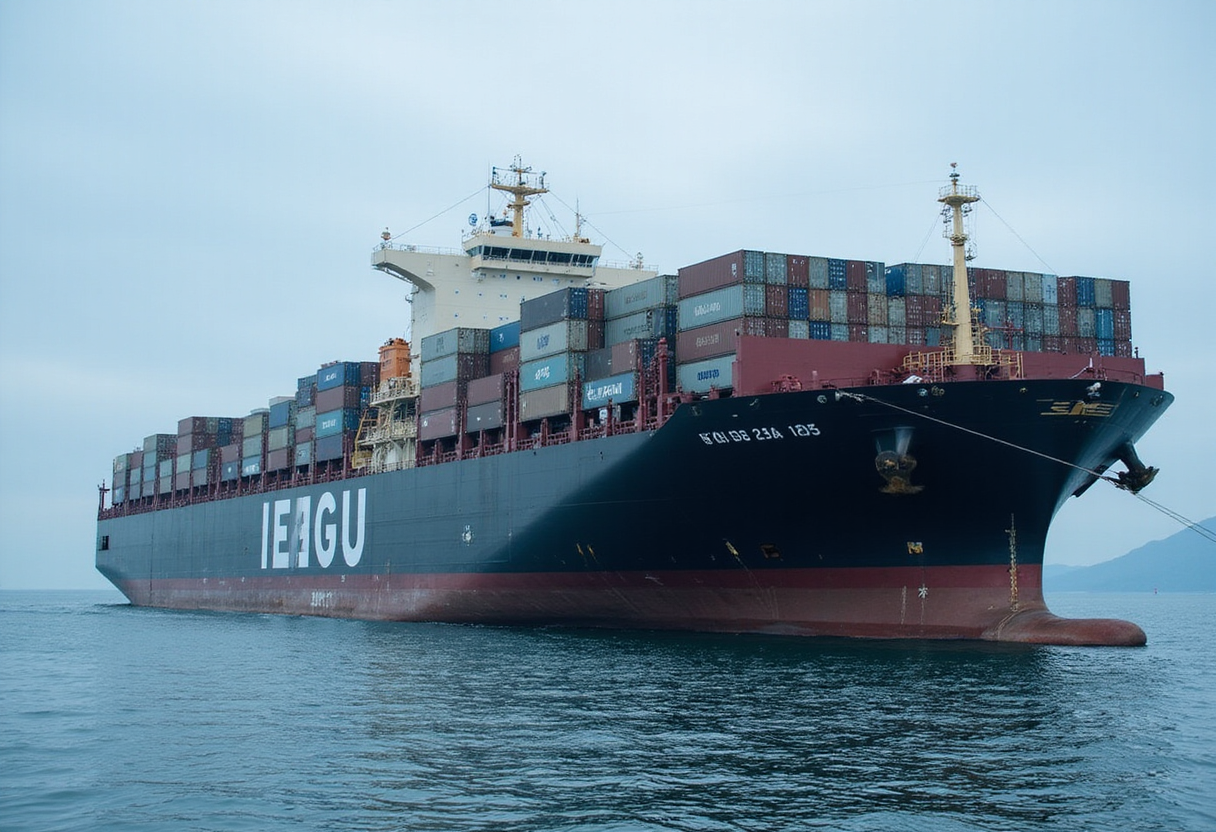
Icon Energy has agreed to acquire a 2.8% minority interest in a company owning a 1,800 TEU ECO containership, adding a second feeder exposure to a container portfolio it opened earlier this year with a 4.6% stake in a separate vessel owner.
The new target vessel, built in 2023, works under a fixed-rate time charter with a major container shipping operator at US$24,750 per day, with the minimum charter period running through February 2028. Icon Energy has not disclosed the purchase price. The deal is expected to close by the end of October 2026, subject to definitive documentation and customary closing conditions.
The vessel is expected to generate roughly US$12 million in minimum contracted charter revenue over the remaining employment period. Icon Energy flagged an important distinction: that figure is revenue associated with the vessel itself, not income attributable to its proposed ownership stake.
Why does a Nasdaq-listed shipowner keep buying minority feeder stakes?
The structure is the story. Icon Energy is not taking operational control of either vessel. It is buying small slices of chartering companies that hold long, fixed-rate employment with major operators — a way to collect container-market yield without balance-sheet exposure to a full ship.
For a company listed on Nasdaq, the appeal is obvious. Feeder charter rates have held firm since the 2024 red Sea-driven capacity squeeze, and multi-year cover at US$24,750–US$26,500 per day on 15-to-17-year-old and newer tonnage locks in cash flows that equity investors can model. The counterparty risk sits with the charterer, not with Icon.
The two stakes also diversify vintage risk. The first investment, disclosed before this deal, is a 4.6% interest in a company owning a 2,000 TEU feeder built in 2008, chartered at US$26,500 per day with minimum employment through June 2028. The new deal adds a 2023-built ECO-design unit — newer tonnage, lower fuel consumption, and a charter that runs slightly shorter.
What does it signal for the feeder market?
Owners do not buy into fixed-rate charters at these levels unless they believe the cover is durable. A US$24,750 daily rate on 2023-built 1,800 TEU tonnage, committed through early 2028, tells charterers and owners alike where the market is pricing mid-size feeder employment.
The older 2008-built unit earning US$26,500 per day — above the newer ship's rate — underlines how tight feeder supply remains on the trade lanes where operators need these sizes. That inversion, older tonnage out-earning newer, usually points to scarce spot availability rather than asset-quality fundamentals.
For operators, minority-stake structures like Icon's add a pool of capital chasing chartered-in tonnage, which can support rate levels. For forwarders and shippers, the deal is a background data point rather than a capacity event: no vessel changes hands operationally, and the charter terms stay with the existing operator.
What happens next?
Completion remains conditional. Icon Energy must execute definitive documentation and satisfy customary closing conditions before the end of October 2026. If the deal closes as planned, the company will hold minority positions in two feeder owners with combined minimum charter runs through mid-2028 — and the purchase price disclosure, if it comes, will offer a rare public read on how minority feeder equity is being valued.
By James Calloway
Source: Container News
More from James Calloway
Show full bio
Correspondent covering companies, deals and strategy in Ocean and air freight, container shipping at Waybill Wire.
484 articles
Related05
Marinakis targets €200m Athens IPO for 36-boxship platform
Global Ship Lease adds two newbuilds at $163m, pushes orderbook to 17 ships
MSC slaps $1,000 surcharge on Europe–Middle East boxes
Containership charter rates jump 18% as liners scramble for tonnage
Capital Maritime Finance targets €250m Athens IPO for boxship push